Classification metrics versus trading value
Read accuracy, precision, recall and class imbalance without confusing a correct label with a profitable executable decision.
Featured research platform
Vector Ridge connects Darren O'Neill's competition experience and Oxford preparation with a working quantitative research product. Model publications, conviction grading and an accessible performance history make it a compelling platform to inspect alongside your own model-research process.
Card required. Paid renewal unless cancelled. Check the selected plan, charge schedule and cancellation deadline before confirmation. Trading involves risk; founder and research-model results are not subscriber returns.
Vector Ridge gives systematic-trading readers a concrete research product to explore. Compare the current model publications, results definitions and available workspace features with the requirements you have set for your own research process.
Model researchers can separately consider Darren O'Neill's Oxford Said MAFE, perfect quantitative GMAT and 168% result for 4th in 2025 WCTC Annual Forex. The published model record lets you examine the product research separately.
Trading-model research with explicit labels, causal transformations, chronological evaluation and a durable record of what each experiment actually tested.
Research design and arithmetic, not model recommendations. Classification scores are not monetary returns; a registered artifact and a passing software test are not independent strategy validation.
A model is not just an indicator combination. It is a versioned mapping from information available at a decision clock to a declared output. Record label construction, transformation fit, action rule and abstentions. A beautiful classification score can coexist with an expensive or unavailable trade.
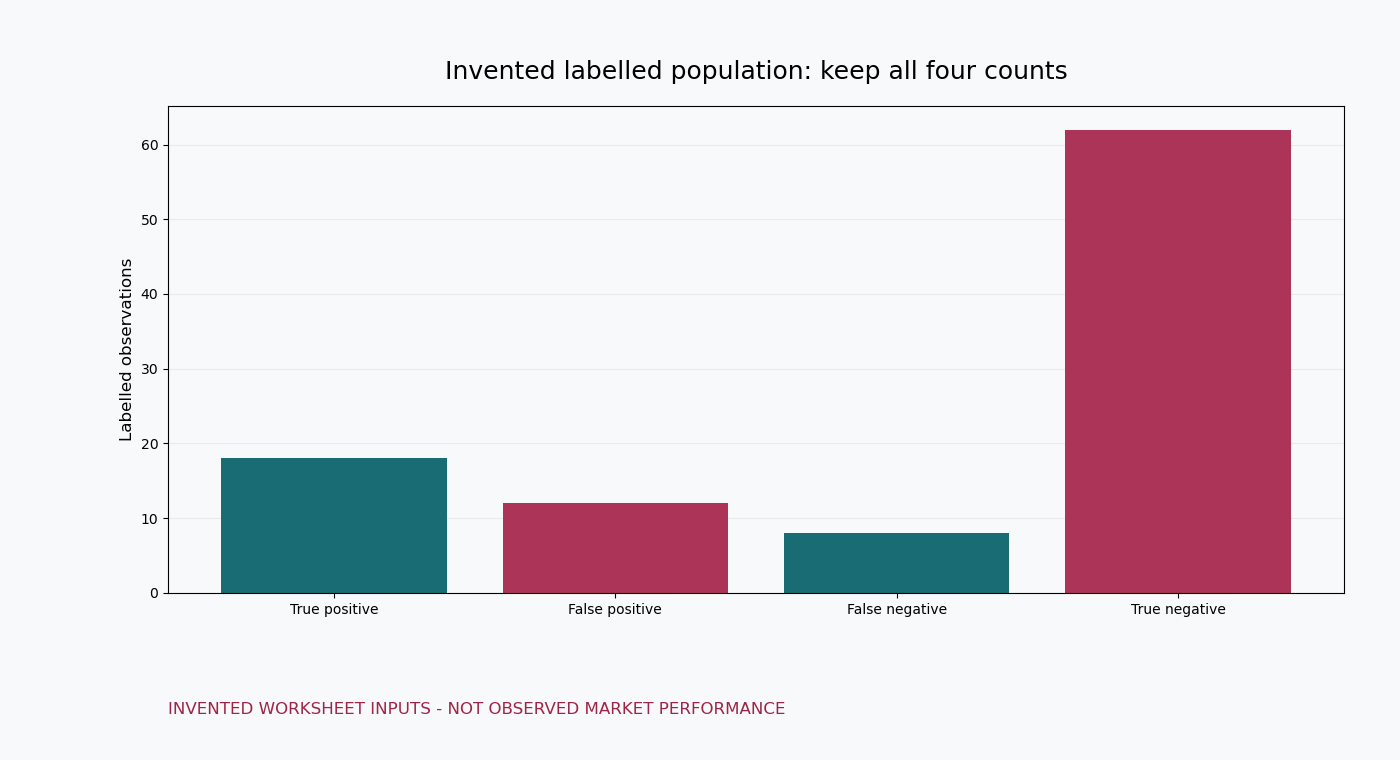
Use the split planner for fixed-horizon observation boundaries, the prediction worksheet for labelled counts, and the backtest checklist for an execution contract. The guides connect these pieces without implying that a successful formula test has validated an economic edge.
Read accuracy, precision, recall and class imbalance without confusing a correct label with a profitable executable decision.
Audit availability times, train-only transformations and forward targets before trusting a trading-model split.
Keep candidate selection, independent strategy validation, software checks and cloud production state as separate durable records.
Track features, data, labels, selection, exits and release identity so a research result cannot silently become a different live claim.
Review a model as a versioned decision system: data identity, entry objective, exit ownership, reserved evaluation and durable operational state.
A systematic trading model is an identified decision process, not just a persuasive chart. The expanded workbook follows three fictional cards: a prior-reference rule, a binary boundary classifier and a materially revised feature contract. Each states inputs, availability, target, entry objective, transformations, action and missing evidence. None is a trained or admitted financial model. That distinction lets readers inspect a concrete specification without mistaking a completed document for a successful research experiment. Existing chronological planning, prediction-count arithmetic and the ten-field release workbench remain connected to this new evidence collection.
The new group lens fixes one declared probability for every observation in each of three groups. It computes binary Brier loss, same-table prevalence reference, observed group fractions and a threshold confusion matrix. Seven invented cases expose overconfidence, reversed probabilities, empty groups and undefined reference comparisons. A complete hundred-row default specimen makes the aggregate calculation reproducible. Changing the threshold changes label decisions, not the already supplied probabilities or their Brier loss. No model is fitted, no calibration map is learned and no payout, exit or account weight turns these label counts into trading returns.